Financing Your Remodel
Some of our clients pay for their project outright. Some prefer to finance part of it, or all of it, and that works well too.
How you finance depends on one thing: how much you need to borrow, not your total project cost.
A $400,000 remodel paid mostly in cash, with $80,000 financed, works differently than a fully financed project. We’ve partnered with two trusted resources to cover both situations.
Financing Up to $200,000:
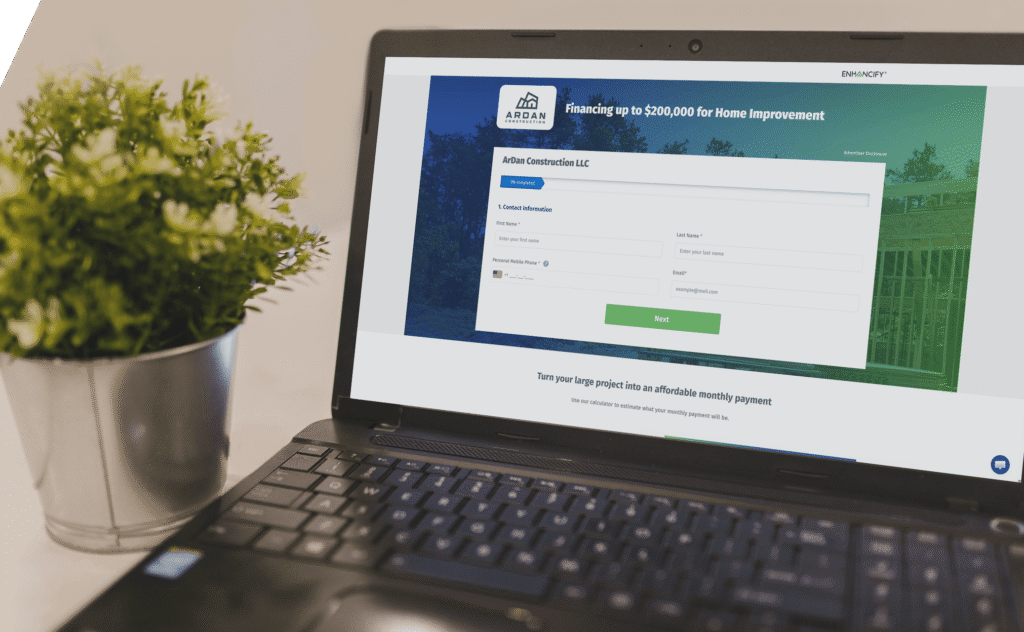
For loans up to $200,000, we work with Enhancify, an online marketplace that compares offers from multiple lenders in one place.
- A short application, about 60 seconds to complete
- Loan amounts up to $200,000, with terms from one to twelve years
- Rates starting at 7.99% APR, with 0% promotional financing available on select offers
- No-collateral options available, starting with a soft credit check
- Funding typically arrives one to five business days after completing the lender’s application
Every offer comes from an individual lender, so your rate, terms, and approval depend on your financial picture. Read the full terms carefully, especially on any promotional offer.
Financing Over $200,000: Liberty Federal Credit Union
For larger projects, we recommend Kate Saethre, a mortgage loan originator at Liberty Federal Credit Union who specializes in construction financing.
Kate offers two paths, and the right one depends on whether you’d like to keep your current mortgage.
Combine Into One New Loan
If you’d rather combine everything into one new loan, Liberty’s construction loan rolls your existing mortgage and your project costs into a single closing.
Keep Your Current Mortgage
If you’d rather keep the mortgage you already have, Kate can walk you through a HELOC instead.
Construction loan highlights:
- One closing for both construction and permanent financing
- Interest-only payments during construction, on funds already disbursed
- A free rate float-down at completion, if your loan qualifies
- A flat $695 construction administration fee
- No limit on the number of draws or inspections
- Room to build a contingency into your original loan amount
Contact Kate Saethre
* Be sure to mention to Kate that you are working with ArDan Construction
Free Guide for Homeowners
Planning to Invest in Your Remodel? Know Who You’re Trusting With It.
- The 3 red flags that quietly derail the most remodels
- The 5 questions that separate a contractor worth trusting from one that only sounds like it
- What to listen for in every answer, so you know what a good one sounds like
By downloading this guide, you’re opting in to receive marketing communications from ArDan Construction, including emails and occasional outreach from our team. You may unsubscribe at any time.
A Few Things Worth Knowing
Bring financing into the conversation early, ideally while we’re still talking through your budget and scope. That gives you time to understand your options, and it helps us build a payment schedule that lines up with your lender’s draw requirements, especially on larger construction loans.
Financing terms, rates, and approvals are determined entirely by the lender, not by ArDan.
We’re glad to point you in the right direction. For specific questions about your rate,
payment, or approval, contact your lender directly.
Frequently Asked Questions
Do I need to finance my whole project?
No. Many clients pay for most of their remodel in cash and finance a smaller portion. Which option applies depends on the amount financed, not your total project cost.
When should I bring up financing?
As early as possible. The sooner we know your plan, the easier it is to finalize a schedule that works for everyone.
Who do I contact with questions about rates or approval?
For Enhancify applications: 813-212-3073 or support@enhancify.com. For loans over $200,000, reach Kate Saethre directly at 480-216-1169 or ksaethre@libertyfcu.org.